If you’re buying or selling a business in the United States, one of the first decisions you’ll face is how the deal is structured — as an asset purchase or a stock (equity) purchase. That single choice shapes almost everything downstream: which liabilities transfer, how the purchase price is calculated, what promises each side has to make, and what obligations linger after closing.
This guide walks through the core mechanics of an Asset Purchase Agreement (APA) — the contract that governs an asset deal — so founders on either side of the table know what to expect and what to negotiate. It’s written for general educational purposes and reflects common U.S. market practice; it is not a substitute for advice from a licensed attorney or accountant who can review your specific transaction.
1. Asset Purchase vs. Stock (Equity) Purchase: The Fundamental Choice
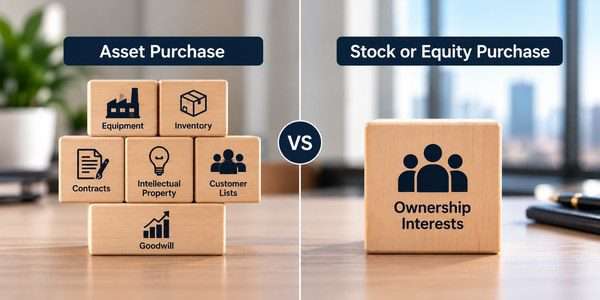
Under U.S. law, a business acquisition is typically structured one of two ways:
Asset purchase: The buyer acquires specific assets and (optionally) specific liabilities of the business — equipment, inventory, contracts, intellectual property, customer lists, and goodwill — rather than the legal entity itself. The seller’s corporation or LLC continues to exist (at least until it’s wound down) and retains whatever assets and liabilities weren’t sold.
Stock or equity purchase: The buyer acquires the ownership interests (shares or membership units) of the entity itself. Because the buyer steps into the seller’s shoes as owner of the whole entity, all of that entity’s assets and liabilities — known and unknown — come along with it, unless the deal documents carve out specific exceptions.
Why does this matter so much? Because the structure drives:
- Liability exposure — asset deals let a buyer be selective about what it takes on; stock deals bring everything, seen and unseen.
- Tax treatment — asset deals often let a buyer “step up” the tax basis of acquired assets, creating future depreciation or amortization benefits; sellers, especially C corporations, may face two layers of tax (entity-level plus shareholder-level) on an asset sale.
- Contract and license transfers — asset deals frequently require third-party consents to assign contracts, leases, and permits; stock deals usually avoid this because the contracting entity doesn’t change, though many contracts contain “change of control” clauses that can still be triggered.
- Deal complexity and timeline — asset deals can involve more paperwork (itemizing assets, obtaining consents, retitling property) but offer more negotiating flexibility over what’s actually being bought.
Quick takeaway Buyers generally prefer asset deals because they can pick and choose what liabilities to assume. Sellers often prefer stock deals for cleaner tax treatment and a full exit. The right structure depends on the entity type, the industry, tax posture, and the specific liabilities in play — it’s a conversation to have early with tax and legal advisors, not an afterthought.
2. Assumed vs. Excluded Liabilities
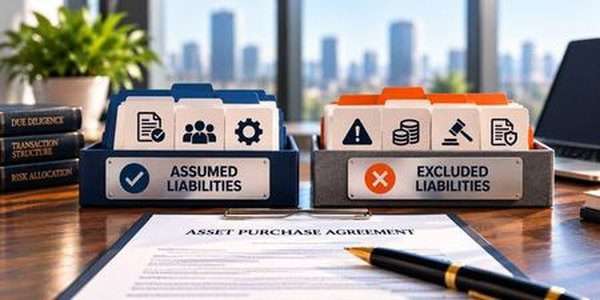
In an asset purchase, one of the most heavily negotiated sections of the APA is the allocation of liabilities. The agreement will typically include two mirror-image lists:
Assumed liabilities: Obligations the buyer explicitly agrees to take on — for example, payables under contracts being assigned, accrued vacation pay for transferring employees, or specific trade payables identified in a schedule.
Excluded liabilities: Everything else, which stays with the seller — commonly pending litigation, tax liabilities for pre-closing periods, unfunded pension or benefit obligations, environmental liabilities tied to prior operations, and undisclosed or contingent liabilities.
Because an asset purchase is designed to let a buyer avoid inheriting unknown liabilities, the assumed liabilities list is usually drafted narrowly and specifically, while the excluded liabilities list is drafted broadly (often ending with a catch-all excluding anything not expressly assumed).
A few liability categories deserve special attention because general liability limitation doesn’t always protect a buyer from them:
- Successor liability doctrines — courts in some circumstances can hold an asset buyer responsible for a seller’s liabilities under theories like de facto merger, mere continuation of the business, or fraudulent transfer, even when the APA says liabilities aren’t assumed.
- Bulk sale and creditor notice rules — some states retain bulk-sale-type notice requirements or lien-priority rules for sales outside the ordinary course of business; local counsel should confirm what applies in the relevant state.
- Employment-related liabilities — obligations under the WARN Act (federal plant-closing and mass-layoff notice requirements), wage claims, and benefit plan liabilities require careful allocation and advance planning if employees are transferring.
- Environmental liabilities — contamination or compliance obligations tied to real property or historical operations can attach to a buyer under federal and state environmental statutes regardless of what the APA says between the parties.
- Tax liabilities — certain state tax authorities can assert successor liability for unpaid sales, use, or withholding taxes; tax clearance certificates are sometimes used to cut off this exposure.
3. Purchase Price Mechanics
How the purchase price is calculated and adjusted is a distinct negotiation from how much is paid in total. Common mechanics include:
Fixed price vs. working capital adjustment: Many deals set a base price and then adjust it up or down based on the target’s working capital (current assets minus current liabilities) as of closing, compared to an agreed target or “peg.” This protects the buyer from the seller stripping cash or inventory before closing, and protects the seller from being shortchanged if working capital is higher than expected.
Escrow or holdback: A portion of the purchase price — commonly a percentage held for a defined period — is placed in escrow or withheld to secure post-closing indemnification claims or purchase price adjustments.
Earnouts: Additional payments contingent on the business meeting agreed post-closing financial or operational targets (such as revenue or EBITDA thresholds) over a defined period. Earnouts help bridge valuation gaps but require carefully drafted metrics, calculation methodology, and operating covenants (how the buyer must run the business) to avoid later disputes.
Purchase price allocation: Buyer and seller typically agree how the total price is allocated among asset classes (for example, under IRS Form 8594 rules for U.S. federal tax purposes) because that allocation affects each side’s tax treatment — capital gains vs. ordinary income for the seller, and depreciation/amortization schedules for the buyer.
Net asset or debt-free/cash-free mechanics: Many APAs are priced on a “cash-free, debt-free” basis, meaning the seller keeps existing cash and pays off existing debt at or before closing, with the purchase price adjusted accordingly at a true-up after closing.
4. Representations and Warranties
Representations and warranties (“reps and warranties”) are factual statements each party makes about itself, the business, or the assets as of signing and/or closing. They serve two purposes: they allocate risk (if a rep turns out to be false, the other side may have a remedy), and they function as a due diligence tool, prompting sellers to disclose problems through formal disclosure schedules.
Typical seller representations in an APA cover:
- Organization, good standing, and authority to enter the agreement
- Ownership and title to the assets being sold, free of liens (except as disclosed)
- Financial statements and their accuracy
- Material contracts and their enforceability
- Litigation, disputes, and government investigations
- Compliance with applicable laws and permits
- Tax matters
- Employee and benefit plan matters
- Intellectual property ownership and non-infringement
- Environmental compliance
- Absence of undisclosed liabilities and no material adverse changes since a specified date
Buyer representations are typically narrower, generally covering organization, authority to enter the deal, financing (if relevant), and the absence of conflicts with other agreements.
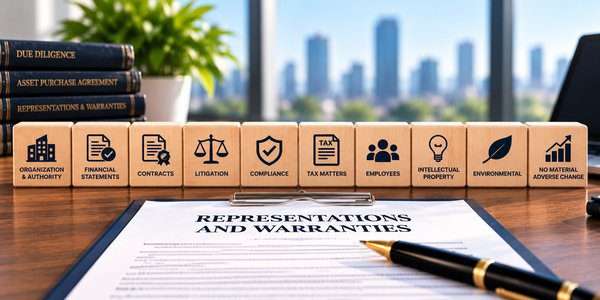
Representations are often qualified by materiality or “knowledge” standards (for example, “to the seller’s knowledge”), and by disclosure schedules that except specific facts from an otherwise broad statement. How these qualifiers are drafted significantly affects each side’s risk.
5. Indemnification
Indemnification is the mechanism that gives reps and warranties (and covenants) teeth: it’s the contractual promise that one party will compensate the other for losses arising from a breach, an excluded liability, or another specified event. Key components typically negotiated include:
Survival periods: How long after closing a party can bring an indemnification claim. General representations often survive 12–24 months; “fundamental” representations (such as title, authority, and capitalization) and certain tax or environmental matters often survive longer — sometimes for the applicable statute of limitations or indefinitely.
Baskets and deductibles: A threshold amount of losses that must accumulate before a party can recover (a “basket”), which may operate as a deductible (only losses above the threshold are recoverable) or a tipping basket (once the threshold is met, all losses are recoverable from the first dollar).
Caps: A ceiling on total indemnification exposure, often tied to a percentage of the purchase price, though caps are frequently carved out or increased for fundamental representations, fraud, and certain specified liabilities.
Escrow as the exclusive remedy (or not): Whether the buyer’s recourse is limited to funds held in escrow or whether it can pursue the seller directly (and its owners, if they’ve provided personal guarantees) beyond the escrow amount.
Representation and warranty insurance: Increasingly common in U.S. middle-market and larger deals, this insurance can supplement or replace traditional indemnification structures, shifting some risk to an insurer for a premium.
Indemnification provisions also typically address the procedure for third-party claims (notice requirements, who controls the defense) and how losses are calculated (whether tax benefits, insurance proceeds, or double materiality counting reduce recoverable amounts).
6. Restrictive Covenants
Sellers (and often key individual owners or executives) are frequently asked to agree to restrictive covenants protecting the value of what the buyer is purchasing:
Non-competition: Restricts the seller from operating a competing business within a defined geography and time period.
Non-solicitation: Restricts the seller from soliciting the acquired business’s customers, suppliers, or employees.
Confidentiality: Requires the seller to keep the acquired business’s confidential information and trade secrets protected post-closing.
Non-disparagement: Restricts negative public statements about the other party after closing.
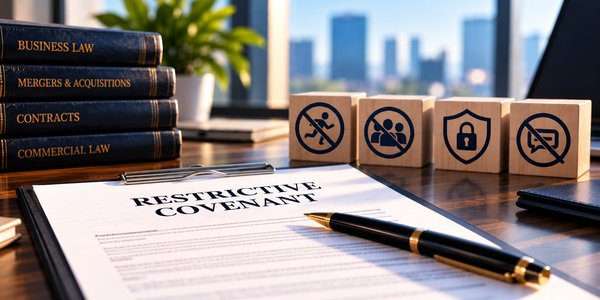
Enforceability of non-competes varies significantly by state. Some states enforce reasonable non-competes tied to the sale of a business (as distinct from employment-based non-competes), while others impose strict limits or, in a small number of jurisdictions, restrict them heavily even in the sale-of-business context. Additionally, the Federal Trade Commission has pursued rulemaking in this area in recent years, and the legal landscape for non-competes has been actively evolving at both the federal and state level — this is an area where current, jurisdiction-specific legal advice is essential rather than optional, and businesses should confirm the up-to-date status of any applicable rule before relying on it.
Courts generally scrutinize the scope (geography, duration, and activities restricted) for reasonableness, and covenants tied to the sale of a business are often given more latitude than employment non-competes because the seller is typically paid a premium in exchange for agreeing not to compete.
7. Closing Conditions
Closing conditions are the requirements that must be satisfied (or waived) before either party is obligated to close. Common conditions in a U.S. asset deal include:
- Accuracy of representations and warranties as of closing (bring-down of reps)
- Performance of pre-closing covenants (e.g., operating the business in the ordinary course between signing and closing)
- Receipt of required third-party consents (landlords, key customers or suppliers, lenders)
- Receipt of governmental approvals or expiration of applicable waiting periods, such as under the Hart-Scott-Rodino Antitrust Improvements Act for deals meeting certain size thresholds
- No material adverse change or material adverse effect on the business since signing
- Delivery of closing documents — bill of sale, assignment and assumption agreement, IP assignments, officer’s certificates, good-standing certificates, lien releases, and escrow agreements
- Completion of any required employee notices or offer letters
- No injunction or law prohibiting the transaction
If a deal signs and closes simultaneously (common in smaller transactions), many of these conditions are addressed at the signing table rather than as a forward-looking gate. In larger deals with a gap between signing and closing, this list becomes a genuine checklist both sides must satisfy.
8. Post-Closing Obligations
The deal doesn’t end at the closing table. Common post-closing obligations in an asset purchase include:
- Purchase price true-up — finalizing the working capital or net asset calculation, often within 60–90 days after closing, with a dispute resolution mechanism (frequently an independent accountant) if the parties disagree
- Earnout measurement and reporting — if applicable, ongoing calculation, reporting, and often audit rights tied to the earnout period
- Transition services — the seller may agree to provide transitional support (IT, accounting, introductions to customers) for a defined period
- Further assurances — cooperation to execute additional documents needed to fully transfer assets, such as vehicle titles, IP assignments recorded with the U.S. Patent and Trademark Office, or real property deeds
- Indemnification claims — the process described above continues to apply for the duration of the applicable survival periods
- Wind-down of the seller entity — if the seller entity isn’t continuing operations, it will typically need to satisfy excluded liabilities, distribute remaining proceeds, and formally dissolve under state law
- Tax filings — final returns, purchase price allocation reporting, and any transfer tax filings required by the applicable state or locality
Frequently Asked Questions
Is an asset purchase always better for the buyer? Not always — it’s generally more protective of the buyer from a liability standpoint, but it can involve more administrative work (contract assignments, retitling assets) and, depending on the seller’s tax structure, may lead to a harder price negotiation since the seller could face less favorable tax treatment.
Do employees automatically transfer in an asset deal? No. Because the buyer is acquiring assets rather than the entity, employees generally do not transfer automatically — the buyer typically extends new offers of employment, and the parties negotiate how continuity of benefits, seniority, and accrued paid time off will be handled.
What’s the difference between a rep and a covenant? A representation is a statement of fact as of a point in time (e.g., “there is no pending litigation”); a covenant is a promise to do or not do something, often over a period of time (e.g., “seller will operate the business in the ordinary course until closing”).
How long does indemnification protection typically last? It varies by deal and by the type of representation, but general representations commonly survive 12 to 24 months post-closing, while fundamental representations and certain tax or environmental matters often survive longer.
Do I need a lawyer for an asset purchase agreement? Given the number of interdependent, heavily negotiated provisions — liability allocation, indemnification, tax treatment, and state-specific issues like non-compete enforceability — engaging experienced M&A counsel and a tax advisor on both sides of the transaction is standard practice in the U.S. market.
This article is provided for general informational purposes only and does not constitute legal, tax, or financial advice. Laws governing business acquisitions vary by state and change over time. Founders considering a business purchase or sale should consult a licensed attorney and tax professional before entering into any agreement.